
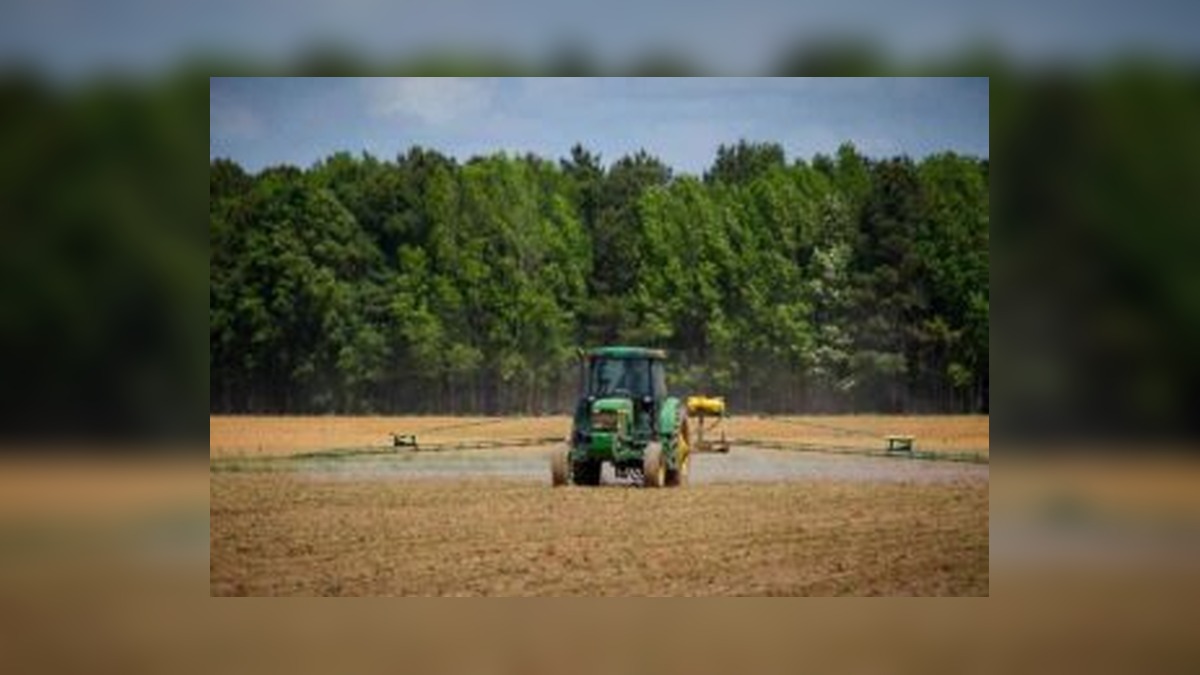
Zimbabwe has issued US$508.8 million in Treasury bonds to former commercial farmers as the Government continues implementing its compensation programme for land acquired during the country’s fast-track Land Reform Programme.
The latest figures were provided in Parliament by Finance, Economic Development and Investment Promotion Deputy Minister Kudakwashe Mnangagwa, who said 623 claimants had received upfront cash payments while the first two batches had also been settled through US dollar-denominated Treasury bonds.
The payments form part of the Global Compensation Deed agreed between the Government and representatives of former commercial farmers in 2020.
First Two Batches Account for US$508.8 Million
The first group comprised 378 former farm owners. They received US$3.19 million in upfront cash, alongside Treasury bonds worth US$305.47 million.
A further 245 claimants made up the second batch. They received US$2.09 million in cash payments and bonds valued at US$203.29 million.
Together, the first two groups account for the US$508.8 million in Treasury bonds issued so far.
A third batch involving 258 claimants has also received upfront cash payments totalling about US$2.15 million, but the Treasury bonds for this group had not yet been issued when Mnangagwa gave the parliamentary update.
Compensation Covers Farm Improvements
The payments are linked to Zimbabwe’s obligations under its land-reform compensation framework.
The Global Compensation Deed provides for compensation to former commercial farm owners for improvements made to agricultural properties that were compulsorily acquired by the State.
Those improvements can include infrastructure and other developments made on the farms. Zimbabwe’s official land-management framework distinguishes this from compensation for the underlying land itself.
Farm owners covered by qualifying Bilateral Investment Promotion and Protection Agreements have different entitlements under the legal framework, including compensation relating to land as well as improvements.
Government’s Wider US$3.5 Billion Commitment
The compensation programme is part of a much larger commitment.
Under the Global Compensation Deed, Zimbabwe agreed to compensate about 3,500 former commercial farm owners for qualifying improvements, with the overall commitment estimated at US$3.5 billion.
The Government has described implementation of the agreement as part of efforts to address outstanding obligations and strengthen confidence in the country’s property-rights framework.
More recent Government figures indicate that the programme has continued to expand since payments began, with the first three batches eventually covering hundreds of approved claims.
Bonds Designed to Provide Long-Term Value
The Treasury bonds are not simply immediate cash replacements.
The compensation framework provides for US dollar-denominated bonds carrying a 2% annual coupon, with maturities extending from two to 10 years depending on the applicable instrument.
The bonds have also been treated as liquid assets and recognised as prescribed assets, giving them potential relevance to institutional investors.
This structure allows the Government to spread the financial obligation over time rather than settling the entire compensation liability in cash immediately.
Potential Listing Could Give Beneficiaries More Flexibility
Another feature of the compensation arrangement is the potential for the bonds to be traded.
Government has indicated an intention to engage the Victoria Falls Stock Exchange over the listing of the instruments. If listed and tradable as envisaged, beneficiaries could potentially sell their holdings before maturity if they need access to cash.
That would give recipients an alternative to waiting until the bonds reach maturity.
Compensation Linked to Debt Resolution Efforts
The Government has repeatedly connected the former-farmer compensation programme with Zimbabwe’s broader arrears clearance and debt-resolution strategy.
The Global Compensation Deed itself was presented as part of efforts to restore confidence in property rights and improve Zimbabwe’s engagement with international investors and financial institutions.
The programme therefore extends beyond the individual payments to former farm owners, forming part of a wider effort to address historical financial obligations associated with the land-reform process.
Programme Continues in Phases
The latest parliamentary figures show that the compensation process remains ongoing rather than being settled through a single payment.
While the first two groups have received both their upfront payments and Treasury bonds, the third batch was still awaiting its bonds at the time of the parliamentary update.
More recent Government reporting has indicated that additional batches of approved claims have subsequently entered the payment process, demonstrating the phased nature of the programme.
For former commercial farmers, the continuing bond issuances represent another stage in Zimbabwe’s attempt to work through compensation obligations that have remained unresolved since the country’s land reform programme.

