
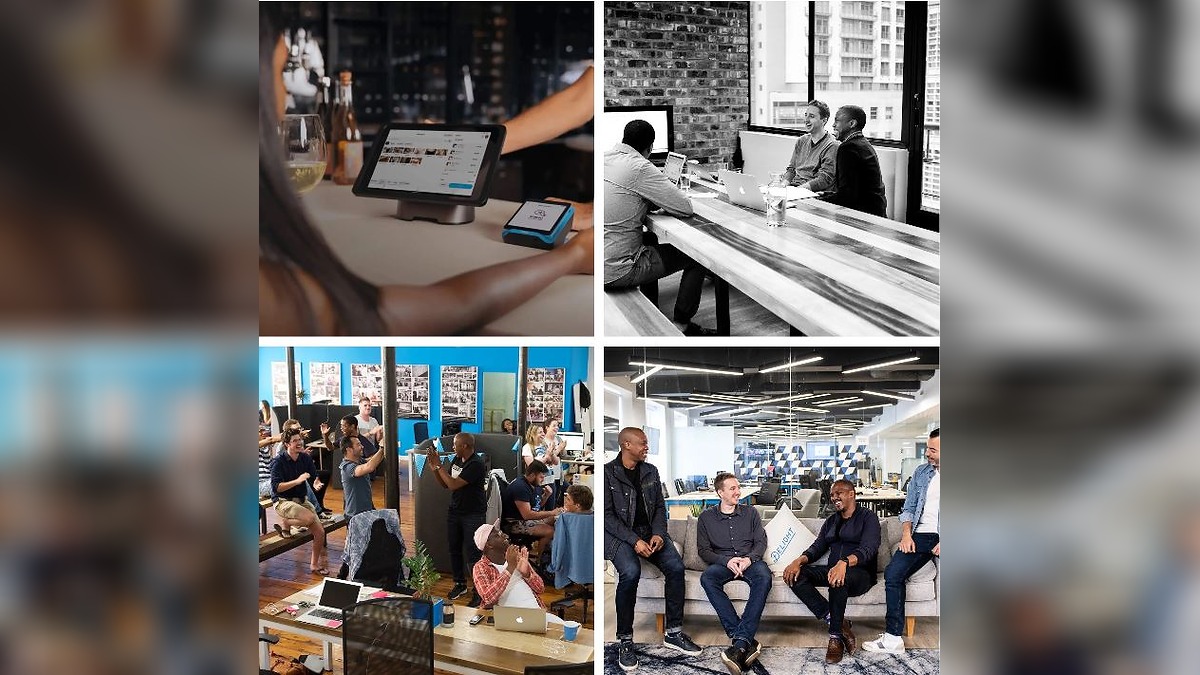
When Carl Wazen, Katlego Maphai, Lungisa Matshoba and Bradley Wattrus began discussing a business idea around 2013, they were not trying to build a major fintech company.
They had no elaborate payments empire mapped out and no polished business plan ready to present to investors. What they had was a frustration they believed was holding back small businesses in South Africa.
“We were all at this stage of our lives where we wanted to do something that had more meaning,” Wazen, who is now Yoco’s chief business officer, recalled.
The four founders came from different professional connections. Wazen and Maphai had worked together at telecommunications consulting firm Delta Partners. Maphai and Matshoba had known each other since childhood and university, while Wattrus had previously worked with Maphai at Rocket Internet in Nigeria.
They entered a South African market that was rapidly adopting card payments but where many small businesses were still struggling to participate.
Between 2010 and 2014, card-payment transactions in the country nearly doubled from 1.02 billion to 1.96 billion, while the number of cards in circulation increased from 58 million to 90 million.
For established businesses, the transition was relatively straightforward. Smaller merchants faced a different reality, with bank applications, complicated processes, fees and payment hardware designed around larger companies.
The founders believed that gap could be addressed with a much simpler approach.
Building a Payments Business Without Becoming a Bank
Yoco’s first proposition was straightforward: give small businesses a simple way to accept card payments.
The company was officially launched in October 2015 after spending about a year in beta with more than 500 merchants. Its first product was a compact card machine that could sit on a shop counter and allow customers to pay using cards already in their wallets.
The hardware was simple. The business behind it was anything but.
Yoco needed banking infrastructure, regulatory compliance, risk controls and a way to convince an established financial institution that four relatively unknown founders could responsibly manage thousands of merchants.
The founders were not attempting to replace South Africa’s banks. Instead, they wanted to use existing banking infrastructure differently, placing a small technology company between traditional payment infrastructure and businesses that had historically struggled to access it.
For a merchant, the difference was intended to be significant: rather than navigating a lengthy bank process and purchasing expensive equipment, the business could sign up more easily, receive a small card reader and begin accepting payments.
The Bank Had to Take the First Risk
Before Yoco could process a single transaction at scale, it needed an acquiring bank.
An acquiring bank provides the infrastructure that allows merchants to accept card payments and connects those transactions to the relevant card networks. For Yoco, finding that partner was arguably more important than building the card machine itself.
The problem was that the startup had no payment history.
“There was an entire year in which we were sitting on 90 days of runway at any moment in time,” Wazen said. “And constantly, that was my only job. I was fundraising the entire time, on a plane, trying to find investors.”
For a commercial bank, backing Yoco meant trusting a new company to acquire legitimate merchants, manage financial risks, support customers and operate within the rules governing payments.
The founders spent their first year trying to make that case.
Wazen compared the proposed arrangement to a mobile virtual network operator, where a smaller company uses the infrastructure of a larger telecommunications provider to serve its own customers.
Yoco effectively wanted to build a large merchant network while relying on a banking partner to provide the underlying payments infrastructure.
The founders eventually produced a detailed business plan covering merchant acquisition, risk management, operations and customer support.
Mercantile Bank ultimately approved Yoco’s application and agreed to provide the infrastructure the startup needed.
Investors Walked Away at the Worst Moment
Securing the banking relationship did not immediately solve Yoco’s funding problem.
The company had already struggled to convince local venture capital firms, partly because it lacked both a trading history and a payments licence. Its first funding round of $560,000 came largely from angel investors, with Wazen using professional relationships in the Middle East to attract early backing.
Among the early supporters were fintech investor Robby Hilkowitz and Greg Kidd, who became an early funder and adviser.
But institutional investment remained difficult.
Yoco found itself trapped in a classic chicken-and-egg problem. The company needed funding to build credibility with the bank, while the bank wanted reassurance that the business would have enough financial resources to operate.
Then came another setback.
An institutional investor that had already issued Yoco with a term sheet withdrew after Mercantile Bank approved the partnership. Wazen has not disclosed why the investor pulled out.
Suddenly, Yoco had the banking relationship it needed but lacked the institutional funding it had expected.
The founders had to decide whether to tell their bank and existing investors about the setback.
They continued anyway.
The angel investors did not leave. Instead, they increased their commitment.
“All the angel investors stayed. They even decided to double down even more to take up the full stake,” Wazen said.
That decision gave Yoco enough money to move forward.
The Founders Became the Sales Team
In the early days, there was no large sales organisation or customer-support department to rely on.
The four founders personally handled onboarding, sales and customer support.
“We were all doing onboarding. We were all doing sales,” Wazen said. “Even when we had a team, we stayed very hands-on when it came to the customer experience, because that’s all we had.”
The product was deliberately designed to be easy enough for merchants to use without formal training.
The strategy initially worked particularly well in Cape Town, where word of mouth helped Yoco build its first merchant community before the company expanded into other South African cities.
The founders were learning directly from the businesses they were trying to serve.
That hands-on approach would later become part of the company’s broader philosophy: problems that appear small when affecting one merchant can become much larger when thousands of businesses encounter them.
A Tenfold Jump Changed the Company’s Trajectory
By 2016, Yoco had its first major evidence that the model could scale.
The company began the year with roughly 500 merchants and ended it with about 5,000.
“That was a 10x growth year,” Matshoba said.
The company then began developing a more repeatable customer-acquisition model through digital marketing, inbound sales and self-service onboarding.
Its growth targets became increasingly ambitious.
In July 2016, Yoco set out to acquire 400 new merchants in a single month, almost three times its previous monthly record of 150.
It reached the target.
By November, the company was adding more than 800 merchants every month.
The next major breakthrough came with Yoco Go, launched in 2019 as a smaller and cheaper card machine designed to reach businesses that remained outside the company’s original customer base.
The response was immediate.
According to Matshoba, Yoco signed up 15,000 merchants in one month, revealing the size of the unmet demand among small businesses.
COVID-19 Put the Entire Model Under Pressure
Then the pandemic exposed just how closely Yoco’s fortunes were tied to the businesses it served.
When South Africa entered lockdown, thousands of businesses reduced their operations or closed temporarily. Transaction activity across Yoco’s platform fell by about 90% at the height of the restrictions.
“Transaction numbers dropped, and we were quite shocked,” Wazen said.
But the crisis also produced information that Yoco could use.
As businesses, investors, government and the wider public tried to understand the economic consequences of lockdown, Yoco began publishing transaction data showing how small businesses were being affected.
It also created a live dashboard tracking recovery patterns across different provinces and industries.
The data offered the company a closer view of its customers’ struggles while simultaneously becoming a resource for understanding the wider small-business economy.
The potential market was substantial. Estimates around 2020 put South Africa’s formal SMME population at about 2.6 million, while the Department of Small Business Development estimated roughly 3.3 million micro and informal businesses.
For Yoco, the crisis therefore raised a fundamental question about the future of physical commerce.
Matshoba rejected the idea that small businesses would simply disappear as commerce became increasingly digital.
“We fundamentally believe that the street is the incubator for any business, especially small businesses,” he said. “If everything becomes digital, you start to get into the world of large corporations.”
Yoco responded by launching online payments and adapting its products as merchants moved between physical and digital sales.
The company also made customer-sensitive decisions designed to help merchants survive the disruption.
Payments Became the Starting Point, Not the Destination
Yoco’s original business was built around one transaction: helping a small business accept a card payment.
Over time, however, those transactions revealed a much broader opportunity.
Once sales were being processed digitally, Yoco could see information about merchants’ transactions and business activity. That opened the door to additional products and services.
Merchants also began asking for more.
They did not necessarily want separate providers for payment processing, point-of-sale software and other business functions. They wanted fewer systems to manage.
“What we didn’t realise that early was how quickly after launching our payments product we would feel the pull from customers for the rest of it,” Matshoba said.
Yoco responded by expanding beyond its original card machine.
In 2020, the company introduced point-of-sale software, online payments and additional business and financial services.
The strategy effectively changed Yoco from a payments company into a broader technology platform for small businesses.
Its underlying philosophy remained the same: stay close to what merchants actually need.
“You’ve got to stay very close to what the customer needs the most from you,” Wazen said.
A Decade of Surviving Change
The environment Yoco entered in 2013 was considerably smaller than South Africa’s current technology and venture-capital ecosystem.
The country has since become one of Africa’s major startup funding markets. In 2025, South African startups raised about $600 million, according to Africa: The Big Deal, representing a 51% increase from the previous year.
Yoco has participated in that growth while navigating its own funding cycles.
The company has raised more than $100 million since its early days, including an $83 million Series C round in 2021, as it expanded its financial and technology offering for small businesses.
Its journey has also included the COVID-19 crisis, changes in consumer behaviour, infrastructure challenges and the broader correction that followed the global startup funding boom.
Wazen believes one important decision was the way Yoco financed its early growth.
Rather than taking substantial institutional funding before the business had established meaningful traction, the founders relied heavily on angel investors during the company’s most uncertain period.
“I think we capitalised ourselves in the right way early on,” he said.
That approach allowed the founders to retain significant ownership and maintain greater control over long-term decisions while building a board and investor group that could provide guidance.
The four-founder structure also played an important role.
“When one was struggling, another could help carry the load,” Wazen said.
The Small Problems That Became a Growth Strategy
Matshoba identifies another lesson from Yoco’s journey: individual customer problems should not automatically be dismissed simply because they affect only one merchant.
“A problem affecting one merchant today could affect thousands in 10 days,” he said.
That mindset encouraged the company to pay close attention to seemingly minor issues before they became widespread problems.
It also reflected the original philosophy behind Yoco: small businesses should not have to accept systems designed primarily for much larger companies.
From a card reader on a shop counter, the company gradually built a wider platform serving around 200,000 small businesses.
Yoco’s Next Chapter Looks Like Another Beginning
More than a decade after the founders first began working on the idea, Yoco is once again confronting the challenge of changing what already works.
The company has accumulated products, technology and infrastructure built over many years, but Wazen believes some of those systems now need to be reconsidered.
“We have built a lot of stuff, but a lot of that stuff was built 10 years ago,” he said. “It’s been great at scale, but there’s definitely going to be a better way of doing it, a more intelligent way of doing it.”
For the four founders, that means the original problem has evolved.
Yoco was initially created to make card payments accessible to businesses that traditional financial systems had struggled to serve. More than a decade later, the company is attempting to determine how technology can help those same businesses manage a much larger share of their commercial lives.
The card machine may have been where Yoco began, but it is no longer where the company’s story ends.

