
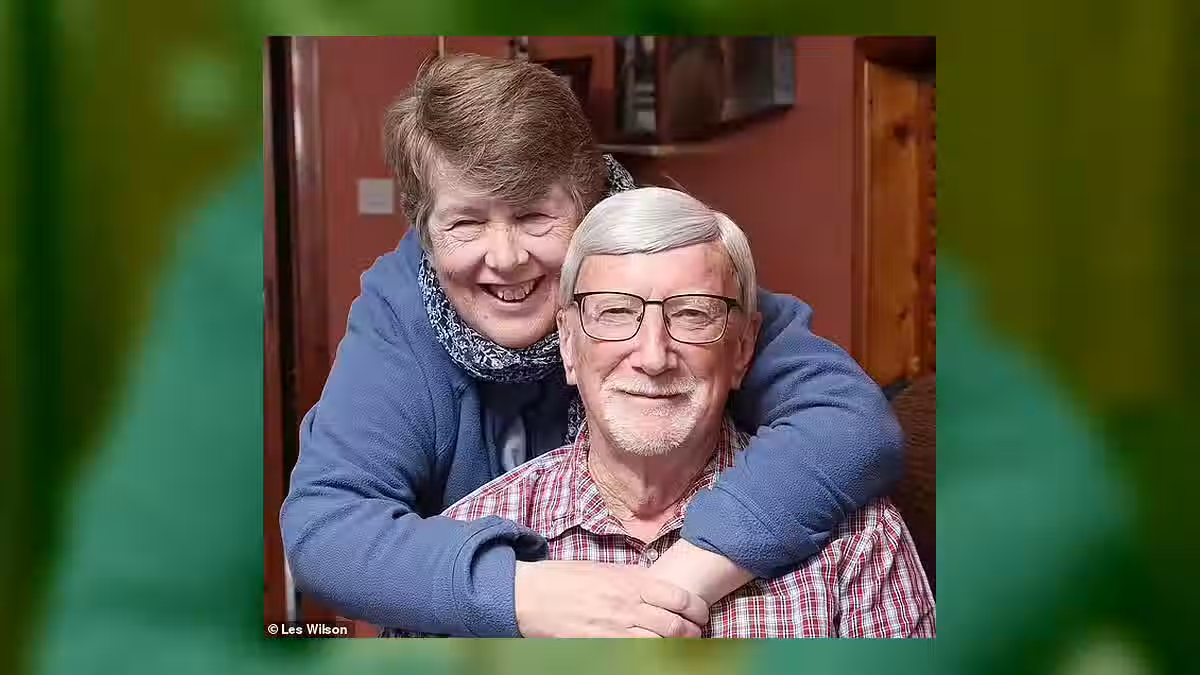
A retired man who paid National Insurance contributions for 48 years is receiving £53 less a week in state pension than his wife, despite her having made contributions for 13 fewer years.
Ron Holdway, 82, and his wife Lesley, who have been married for 45 years and live in Wiltshire, have experienced the difference between Britain’s two state pension systems.
Lesley, 66, receives £53 more every week, equivalent to £2,756 annually. She has 35 qualifying National Insurance years and receives the full new state pension, while Ron’s pension is calculated under the system that applied before April 2016.
The difference means Lesley could receive approximately £55,000 more than her husband over a 20-year retirement, based on the current weekly gap.
Different Retirement Dates Put Couple on Separate Systems
Ron reached state pension age in 2009, meaning his payments are calculated under the previous system. Lesley reached pension age last year and qualifies under the flat-rate system introduced in April 2016.
The older arrangement consists of a basic state pension, currently £184.90 a week, alongside any additional earnings-related payments built up during a person’s working life.
The newer system replaced this structure with a single payment that is not directly determined by a person’s former salary. The full new state pension currently stands at £241.30 a week, £56.40 above the basic rate under the old arrangement.
To qualify for the full new state pension, most people need 35 years of National Insurance contributions or credits. Under the previous system, 30 qualifying years were generally required, although the number could reach 44 depending on a person’s date of birth.
Self-Employment Affected Ron’s Pension Entitlement
Ron, a retired chartered accountant, was self-employed during his working life. This meant he could not contribute towards the additional earnings-related pension arrangements known as SERPS or the State Second Pension (S2P).
He said he would have paid more into the system if he had been given the opportunity.
Lesley previously worked as a policewoman before becoming a secretary in her husband’s business. She later received National Insurance credits for caring for her grandchildren, helping her reach the 35 qualifying years required for the full new state pension.
Although both pensions increase under the annual triple lock, the difference in their starting amounts means Lesley receives a larger cash increase.
For the next annual adjustment, the new state pension is due to rise by 3.9 per cent, giving Lesley an additional £9.40 a week. Ron’s basic state pension will increase by approximately £7.20.
“Every year that goes by the differential gets bigger. Other people I know who were self-employed are in the same position as me,” Ron said.
He has written to his MP and the Department for Work and Pensions about the difference, but said the responses he received were standardised.
Older Pensioners Question Fairness of the System
The Holdways’ experience reflects complaints from pensioners who retired before April 2016 and believe the current arrangements favour younger retirees.
Money Mail reported receiving numerous letters from readers, particularly those in their mid-70s and older, following the announcement of the next state pension increase.
Paul Green, 80, a retired chartered surveyor from Derbyshire, receives £192 a week and said he considered the difference between the systems unfair.
He said he had worked hard throughout his career and believed the issue was about the principle of how pensioners were treated.
Earnings-Related Payments Complicate Comparisons
The previous state pension system included additional payments that were not available to everyone. These began with Graduated Retirement Benefit and later included SERPS and the State Second Pension.
Workers who contributed towards these arrangements could build up additional pension entitlement on top of their basic state pension.
From 1978, some employees also accumulated SERPS entitlement through workplace pension arrangements. Those who qualified continue to receive the additional payments alongside their basic pension.
However, some workers and employers chose to contract out of the additional National Insurance contributions required for these benefits. In return, they received rebates that increased their workplace or private pension provision.
This arrangement reduced their entitlement to additional state pension payments but could leave them with larger private pensions in retirement.
Some older pensioners who built up substantial additional entitlements now receive more than £20,000 annually, considerably above the current full new state pension of £12,547.60 a year.
Former Pensions Minister Says Comparisons Can Be Misleading
Sir Steve Webb, who helped develop the new state pension while serving as pensions minister, said comparisons based only on the basic old pension and the full new rate did not reflect the entire system.
He said the old arrangement included additional payments that needed to be considered when comparing pensioners’ incomes.
Webb, now a partner at pension consultancy LCP, also said not everyone receiving the new state pension qualified for the full flat-rate amount.
According to him, the actual difference between people receiving the old and new state pensions was less than £10 a week on average, with stronger National Insurance records among newer retirees contributing to the gap.
Official figures for March showed that more than 7.8 million people receiving the old state pension were paid an average of £207.78 a week. Around 5.4 million people on the new state pension received an average of £216.42.
Webb also said the legislation introducing the new system in 2016 was expected to reduce government spending compared with the previous arrangements.
He acknowledged that people on the new system benefit from having their entire pension increased through the triple lock, but said they lost the opportunity to build up additional state pension entitlements after the reforms.
Triple Lock Increases Affect Older Pensioners Differently
The triple lock guarantees that the state pension rises each year by whichever is highest among inflation, average earnings growth or 2.5 per cent.
However, the mechanism does not apply equally to every part of the old state pension.
For people receiving the new state pension, the full payment is increased according to the triple lock. For those under the previous system, the guarantee applies only to the basic state pension.
Additional payments, including Graduated Retirement Benefit, SERPS and S2P, rise in line with inflation rather than the triple lock.
Under the announced rates, the old basic state pension is due to increase from £184.90 to £192.10 a week next April. The full new state pension is expected to rise from £241.30 to £250.70, equivalent to just over £13,000 annually.
The different calculation methods have contributed to complaints from older pensioners whose total payments have not increased at the same rate as the full new state pension.
Former Pensions Minister Raises Concerns Over Older Retirees
Baroness Altmann, another former pensions minister, said she regularly heard from older people who believed their payments had fallen behind those of younger pensioners.
She said pensioners whose income included additional state pension payments had not benefited fully from the triple lock, even when their total weekly payments were close to the new state pension rate.
Rachel Vahey, head of public policy at AJ Bell, said people who depended heavily on SERPS income could feel overlooked as its value gradually fell behind the newer state pension.
She said policymakers should continue addressing the issue rather than treating it as a problem affecting only previous generations.
Government Considers Changes to Pension Increases and Tax
Prime Minister Andy Burnham has announced plans to replace the triple lock with a double lock in future.
Under the proposed arrangement, annual increases would be determined by whichever is higher between inflation and 2.5 per cent, removing the automatic link to wage growth each year.
Burnham has nevertheless pledged to maintain an earnings link in the longer term, with the proposed arrangement due to begin in 2030 if he wins the next election.
The Government has also announced a separate income tax allowance for pensioners whose total income is no higher than the full new state pension.
From next April, the proposed pensioner tax allowance will be £13,036.40, matching the expected annual value of the full new state pension. This would replace the standard £12,570 personal allowance for eligible pensioners and apply to people receiving either the old or new state pension.
DWP Says Fairness Has Been Considered
A Department for Work and Pensions spokesperson said supporting pensioners remained a priority and that consideration had been given to ensuring fairness for people receiving both the basic state pension and the new state pension.

