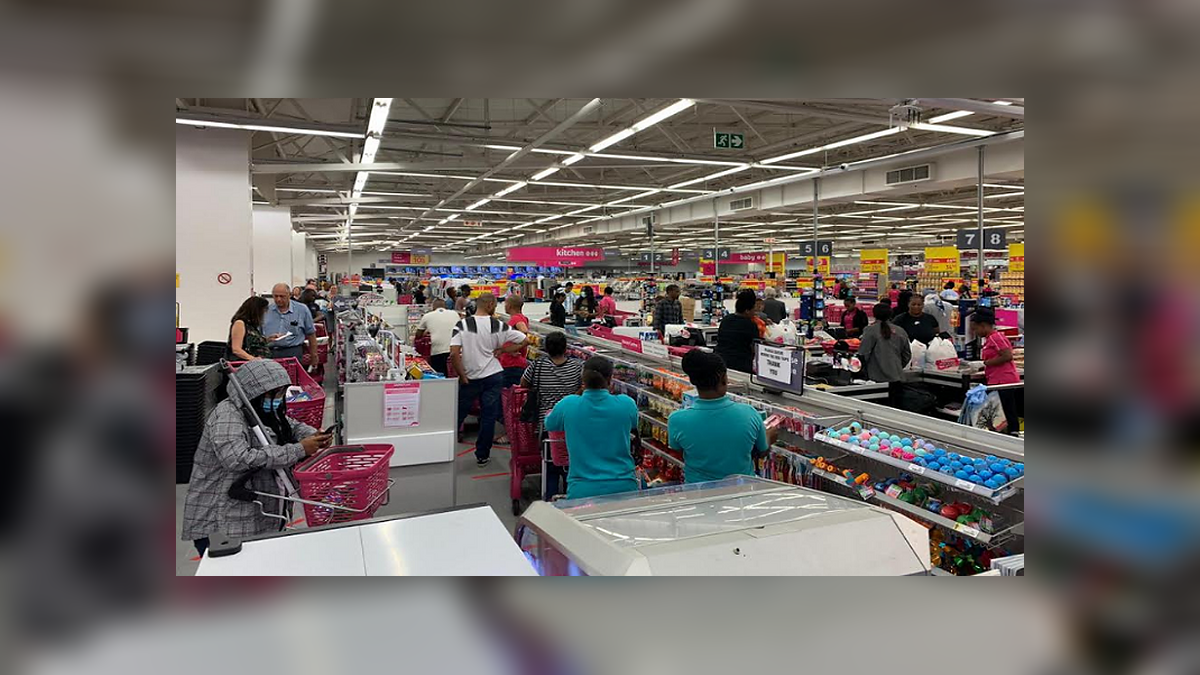
South Africans have been urged to carefully assess their finances before taking advantage of Black Friday promotions on November 27, with the National Financial Ombud (NFO) warning that purchases made on credit could cost significantly more than advertised prices.
The warning comes as retailers prepare to attract shoppers with discounts, limited-time deals and flexible payment arrangements.
Nerosha Maseti, Banking and Credit Lead Ombud at the NFO, said consumers should look beyond the immediate savings and calculate the full amount they would eventually repay.
She explained that although discounts reduce the original purchase price, financing an item creates a financial commitment that continues after the promotional period has ended.
Maseti said shoppers should consider how repayments will affect their ability to cover other household and financial obligations.
Monthly Instalments Can Conceal the Full Cost
The NFO warned that seemingly manageable monthly repayments can make credit purchases appear more affordable than they actually are.
For example, a product costing R6,000 financed over 24 months at R350 per month would require total repayments of R8,400.
This means the buyer would pay R2,400 more than the original price, representing an additional 40%. Interest, administrative fees and compulsory insurance can contribute to the higher cost.
Maseti said consumers should assess instalments alongside their existing loans, household expenses and other financial commitments rather than considering each repayment separately.
She acknowledged that borrowing is commonly used by households to manage expenses but stressed the importance of understanding the long-term financial consequences.
Buy Now, Pay Later Could Increase Household Commitments
The NFO also expects Buy Now, Pay Later (BNPL) services to attract more shoppers during Black Friday promotions.
Some BNPL arrangements allow consumers to spread payments without paying interest. However, the Ombud warned that the convenience of deferred payments could encourage shoppers to make several purchases without considering their combined cost.
Four separate purchases carrying monthly repayments of R500 each, for instance, would create a total monthly obligation of R2,000.
Maseti said consumers should recognise that smaller deferred payments still come from the same household income used to cover other expenses.
The Ombud also reminded shoppers that approval for credit under the National Credit Act 34 of 2005 does not necessarily mean the borrowing is financially sustainable for them.
Consumers must independently assess whether they can afford repayments, while credit providers are required to meet their legal assessment obligations. Applicants are also expected to supply accurate financial information.
Returning Defective Goods Does Not Automatically Cancel Credit
The NFO highlighted another issue that shoppers should consider when purchasing goods through credit agreements: disputes involving defective products, undelivered items and returns.
Sections 55 and 56 of the Consumer Protection Act provide consumers with the right to return defective goods within six months for a repair, replacement or refund.
However, returning an item to a retailer does not automatically terminate a separate credit agreement used to finance the purchase.
According to Maseti, the outcome depends on the financing arrangement, the circumstances surrounding the return and the applicable legal provisions.
Consumers who return financed goods should immediately notify their credit providers, obtain written confirmation of any refund from the retailer and check that the outstanding loan balance has been adjusted correctly.
NFO Issues Guidelines for Black Friday Shoppers
The Ombud has outlined several steps consumers should take before committing to Black Friday purchases.
- Calculate the full repayment amount: Compare the total cost of an item, including interest, administrative fees and insurance, rather than focusing only on its discounted price.
- Set a spending limit: Establish a realistic budget that allows essential household expenses to be covered.
- Review existing debts: Include current loans, store accounts and BNPL repayments when calculating how much additional credit can be afforded.
- Avoid promotional pressure: Do not allow limited-time offers to influence decisions involving long-term financial commitments.
- Read credit agreements: Check repayment conditions, charges, cancellation provisions and the consequences of missing payments.
- Keep transaction records: Retain purchase receipts, credit agreements, repayment schedules and written confirmation of returns or refunds.
- Resolve problems quickly: Contact the retailer and credit provider when disputes arise, and confirm that agreed refunds or account adjustments have been processed.
Consumers Advised to Contact Credit Providers Before Approaching Ombud
The NFO said consumers experiencing difficulties with participating non-bank credit providers should first try to resolve their complaints directly with the relevant institutions.
If a dispute remains unresolved, the organisation’s Banking and Credit Division may consider qualifying complaints involving disputed balances, incorrect account adjustments, interest and charges, credit bureau reporting, and other matters relating to credit agreement disputes and fraud.
Consumers can contact the National Financial Ombud on 0860 800 900 or email info@nfosa.co.za. Further information is available at www.nfosa.co.za.
The warning was issued ahead of Black Friday on November 27, as shoppers prepare to take advantage of promotional offers from retailers across South Africa.
